
How your application works
Five steps from the first form to a complete file. Having the right documents ready is the best way to avoid delays.
A 38-second walkthrough
See each step of the application and the documents to have ready. Captions are available.
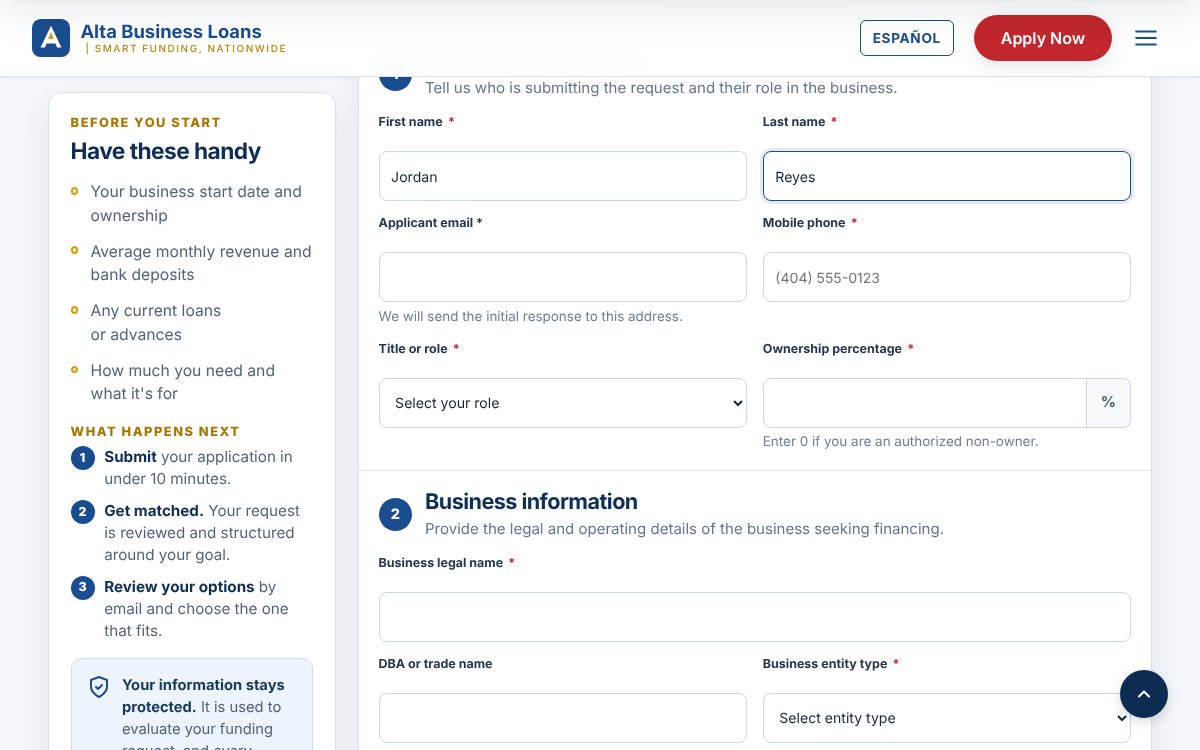
Prequalify in a few minutes
Start with the short form on the application page: your contact details, your business, how much you need and a few questions about revenue and credit. Estimates are fine. There is no hard credit pull to apply.
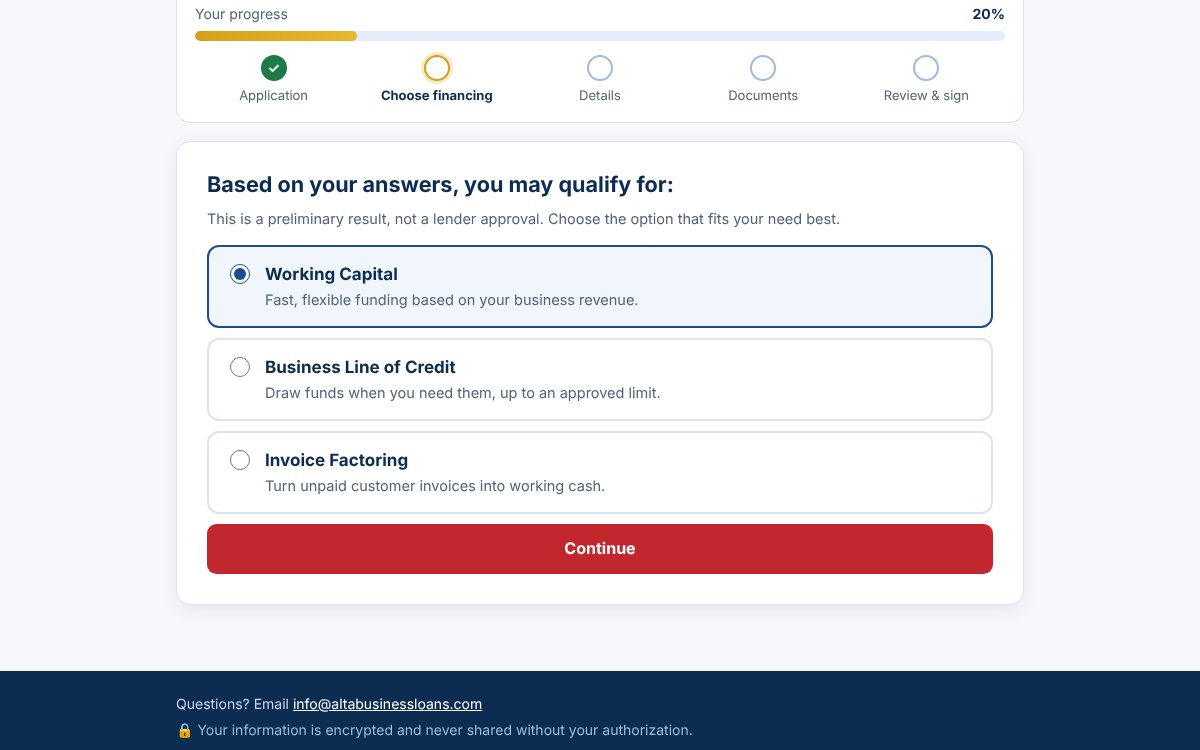
See the options you may qualify for
Right after you submit, you sign in to your secure portal with a one-time code we email you. It shows the financing options you may qualify for, based on your answers. Choose the one that fits your need.
This is a preliminary result, not an approval or a guarantee of funding. Lenders review your complete application and make the final decision.
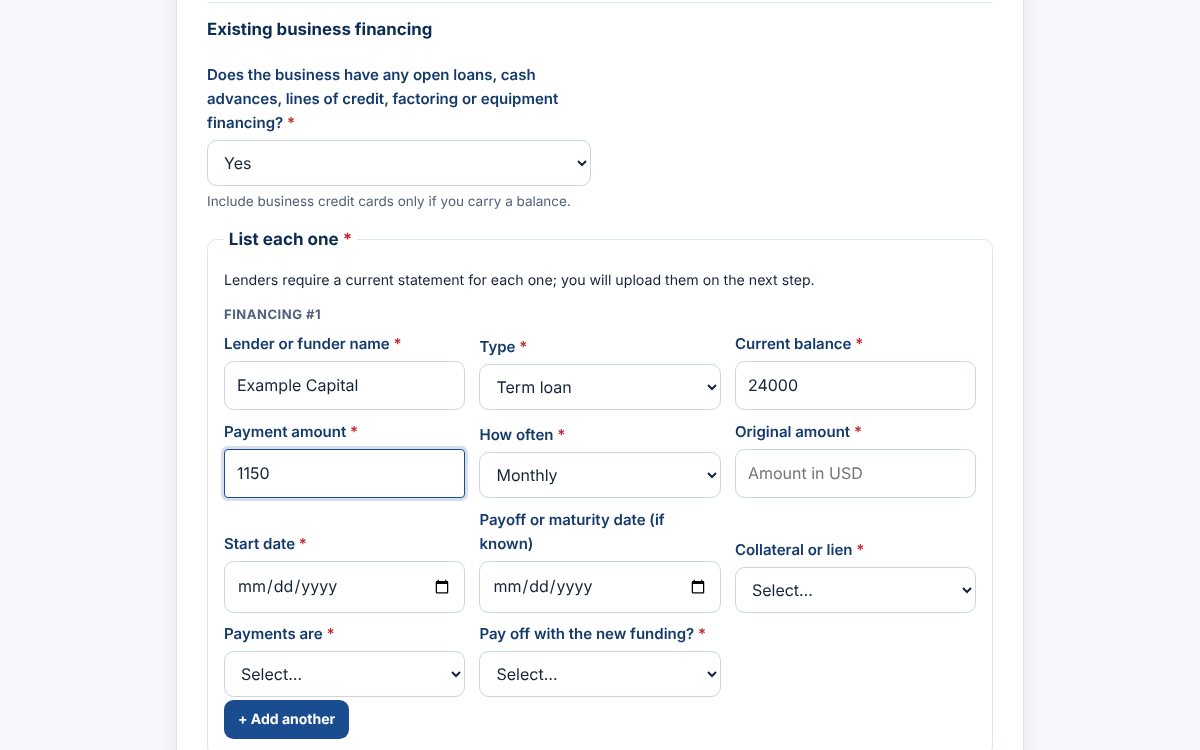
Complete the full application
A few more details lenders ask for, in plain questions. Some questions appear only when they apply to you:
- Each current loan, cash advance or line of credit: lender, balance, payment and how often you pay
- How you will use the funds, broken down by amount
- How the payments will be covered and what is driving your timeline
- Other owners with 20% or more
You can save and come back as many times as you need.
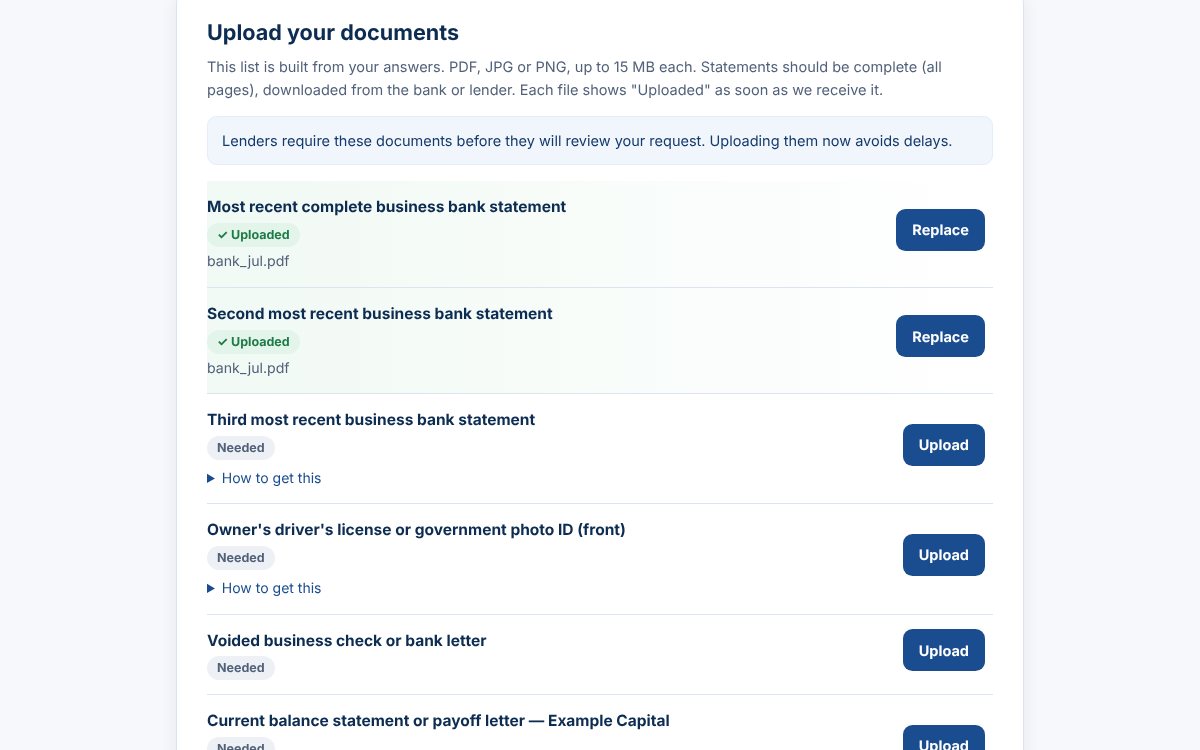
Upload your documents
Your document list is built from your answers, so you are only asked for what applies to you. Each item has a short “How to get this” tip. Files show “Uploaded” as soon as we receive them.
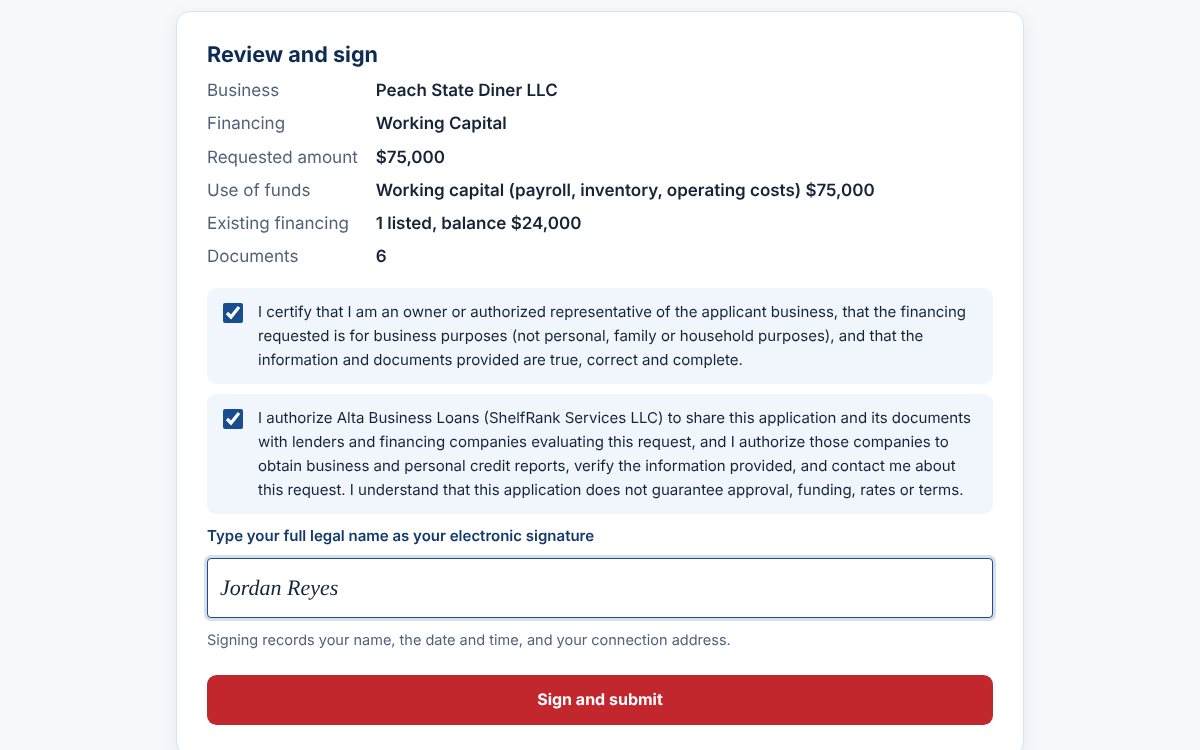
Review and sign
Check the summary, confirm the two statements and type your name to sign electronically. Your file is then reviewed and submitted for funding review, and we email you with updates.
Documents to have ready
Most applicants need the first group. The second depends on your answers.
Almost everyone
- Your last three complete business bank statements (PDFs downloaded from your bank, all pages)
- A photo ID for the owner
- A voided business check or a letter from your bank
Only if it applies to you
- A current statement (within 60 days) for each loan, cash advance or line of credit, plus the agreement for each cash advance
- Your factoring agreement and latest statement, if you factor invoices today
- An equipment quote or invoice, if the funds are for equipment or vehicles
- The contract or purchase order, if the funds are for a specific job
- Your tax payment-plan or paid-in-full letter, if you have a tax lien or tax debt
- A business plan with projections, if your business is under two years old or you choose an SBA loan
Prequalification is not an approval or a guarantee of funding.